Chargeback Prevention and Dispute Management

Stop Chargebacks Before They Start

How authorization data, delivery proof, and early alerts fit together so a disputed order is resolved with evidence instead of a refund.

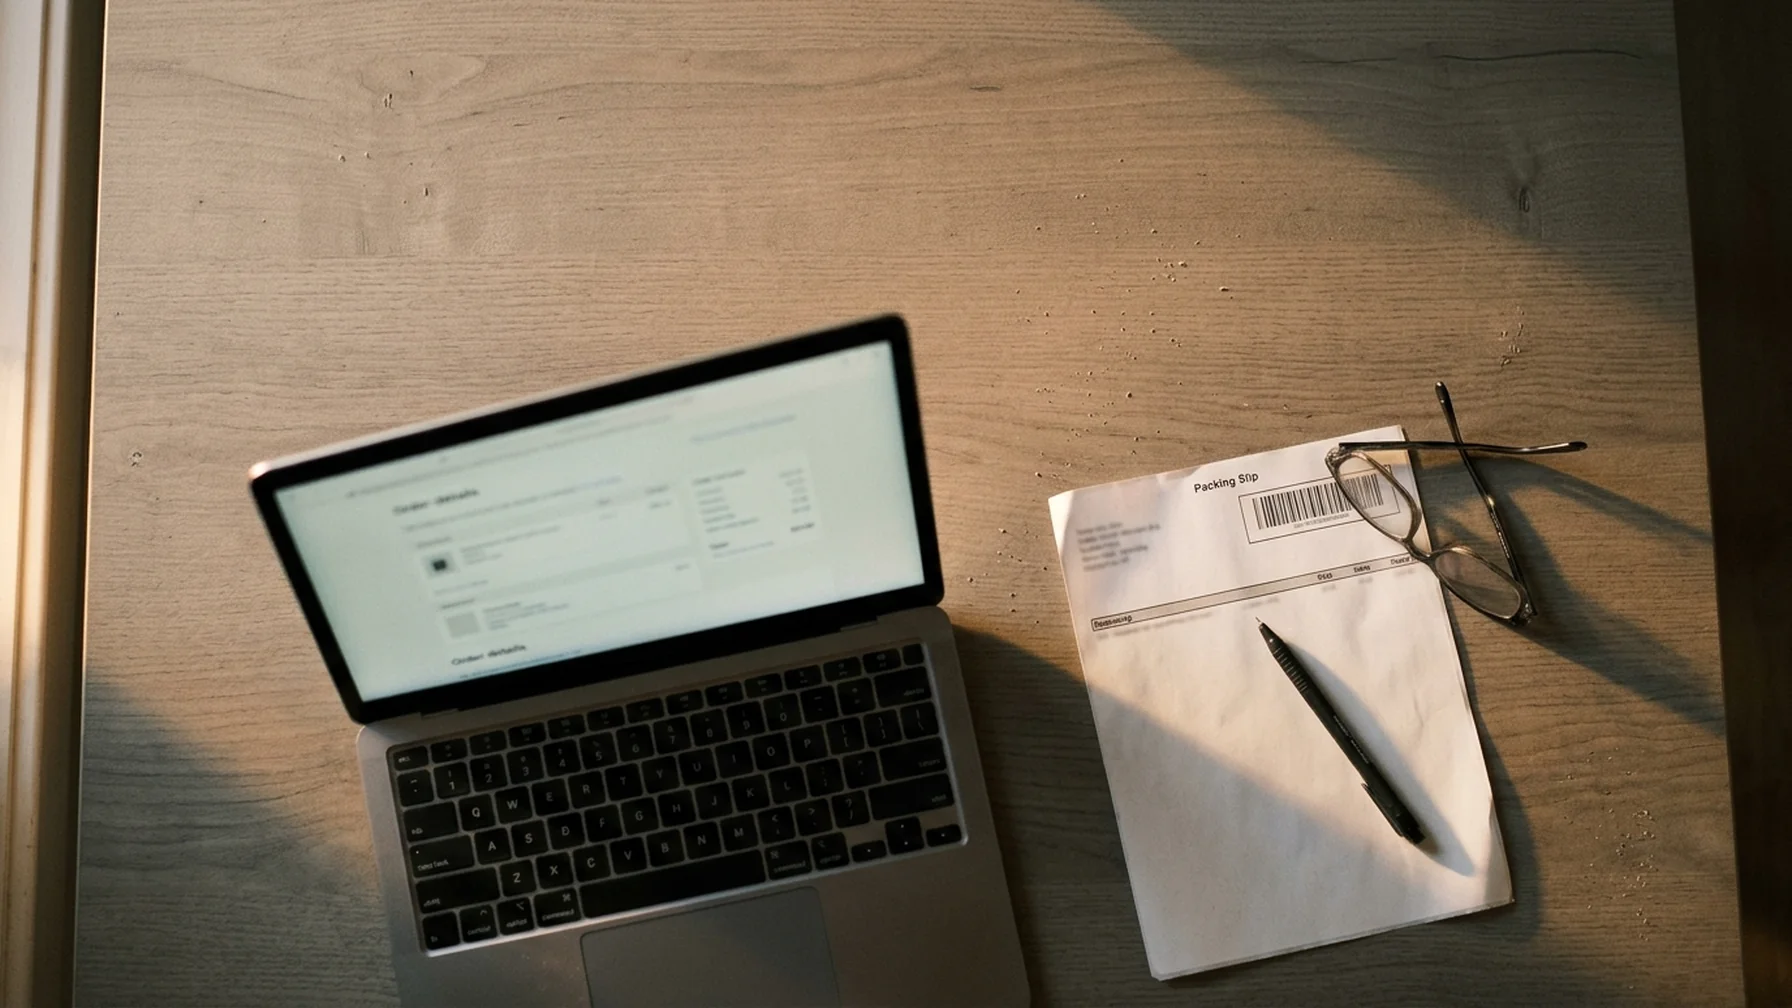
Close-up of a merchant's desk with a laptop showing an order detail screen, a printed packing slip, and a shipping label beside a pair of reading glasses under soft window light

What You Get From This Guide

Each section is built around a decision a merchant actually has to make, not a vendor pitch.

01

Spot Fraud Before the Chargeback

Learn how card testing, stolen-card orders, and account takeover show up in your order data, and which signals are worth acting on. The goal is fewer bad orders approved without blocking good customers.

Payment fraud detection
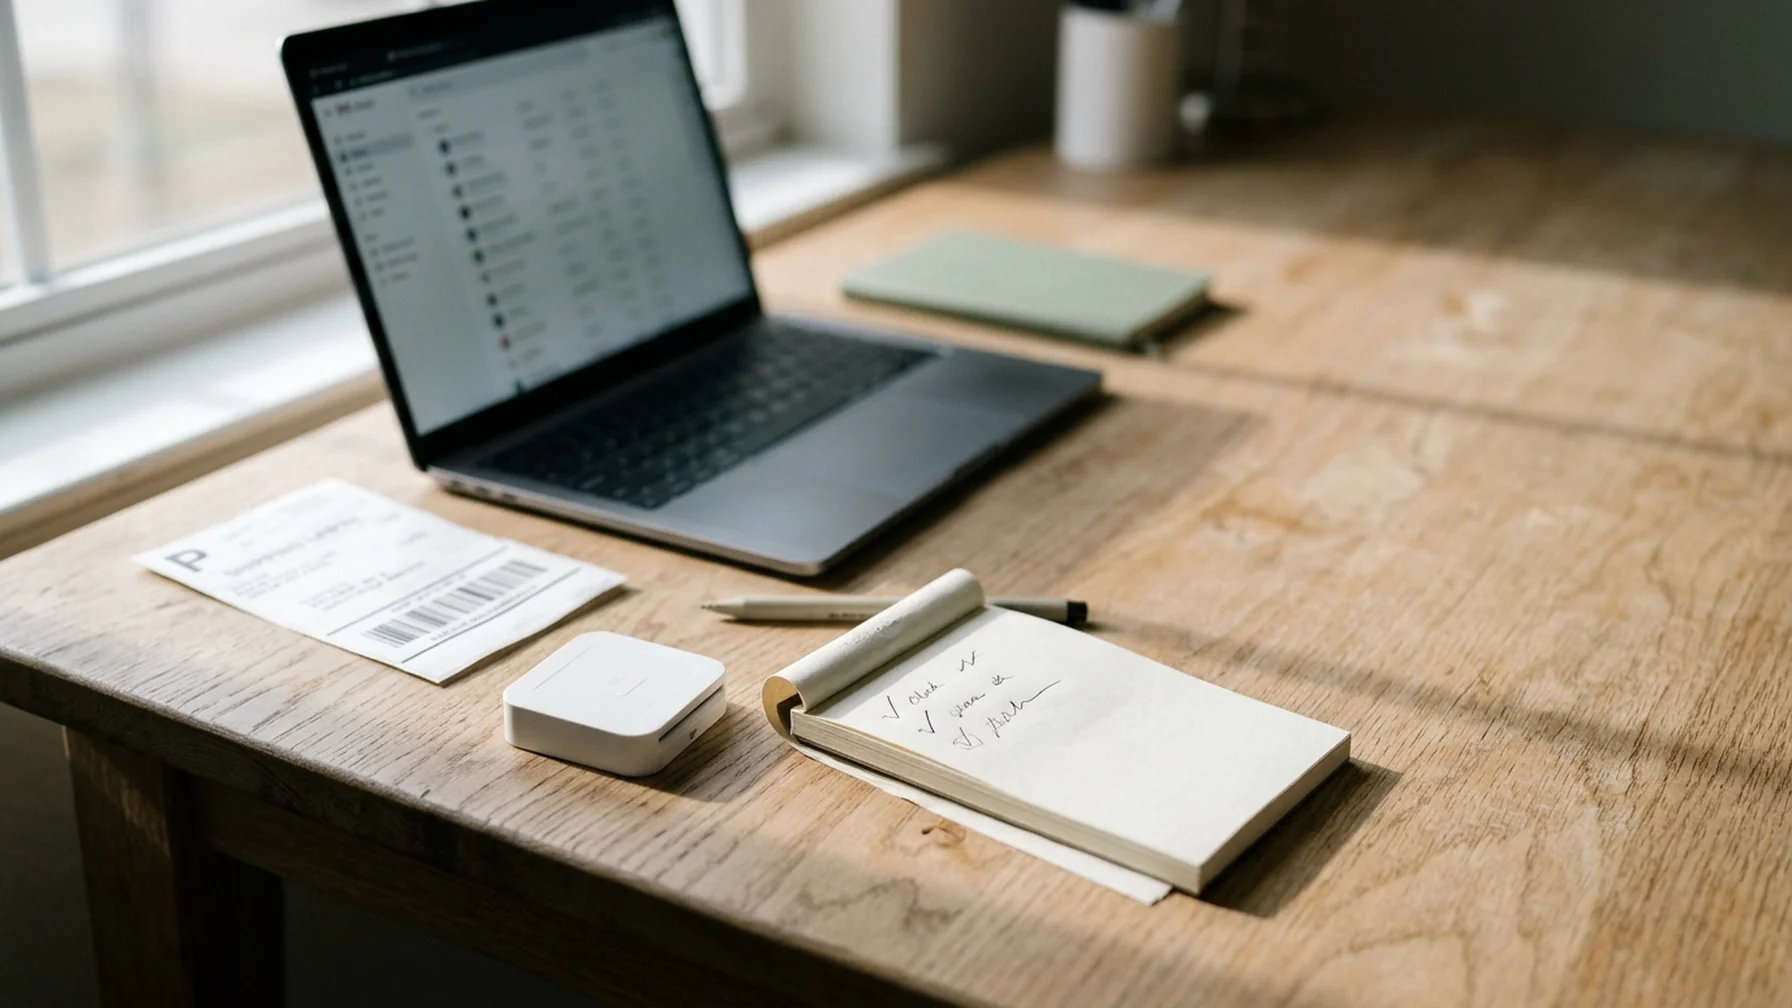
A merchant's desk with a laptop showing an order review queue, a printed shipping label, and a card reader at the edge of the frame, lit by window light.

02

Build a Chargeback Response You Can Repeat

See how evidence requirements differ by reason code, what to collect at checkout and fulfillment, and where deadlines usually slip. Includes how to tell a winnable dispute from one worth accepting.

Chargeback prevention and disputes
A person assembling dispute evidence at a desk, with printed order records sorted into stacks beside a laptop.

03

Set Risk Rules That Match Your Margins

Compare review thresholds, velocity limits, and manual review costs against your average order value. A rule that works for a $400 order rarely works for a $12 one, and the guide shows where that gap bites.

Risk operations and policies
A wall-mounted screen in a small office showing a simple line chart of order volume, with a notebook and coffee cup on the desk below.
Close-up of a laptop on a wooden desk showing an order confirmation email with a merchant name and billing amount, a card and notebook beside it in soft window light.

Chargeback Prevention

Fewer chargebacks start with clearer billing

Most disputes trace back to a charge the cardholder did not recognize, so the descriptor and receipt are the first place to fix.

  • Match the billing descriptor to the name shoppers see on your site and in confirmation emails.
  • Send a receipt at purchase that repeats that descriptor and the support contact.
  • Make cancellation and refund paths visible before the cardholder calls the bank.
Read chargeback prevention guides

Chargeback Prevention That Holds Up

Three parts of a dispute program that decide whether you win the case or prevent it from being filed.

A merchant's desk with a printed order confirmation, a shipping label and a laptop showing a delivery tracking page

Evidence a bank will accept

Issuers weigh proof that the cardholder authorized the purchase and received what was described. Order confirmations, delivery tracking, device and IP data, and prior purchase history each answer a different claim code. Collect them at checkout and shipment, not after the dispute arrives, because most networks set short response windows.

Build a chargeback evidence file
A risk analyst reviewing order screening rules on two monitors in a dim office

Rules that stop the charge before it ships

Velocity limits, address verification, CVV checks and blocklists catch some fraud, but each one also rejects paying customers. Set thresholds from your own decline and dispute history, then review them monthly. A rule that blocks a $12 order and a rule that blocks a $900 order should not look the same.

Set order screening rules
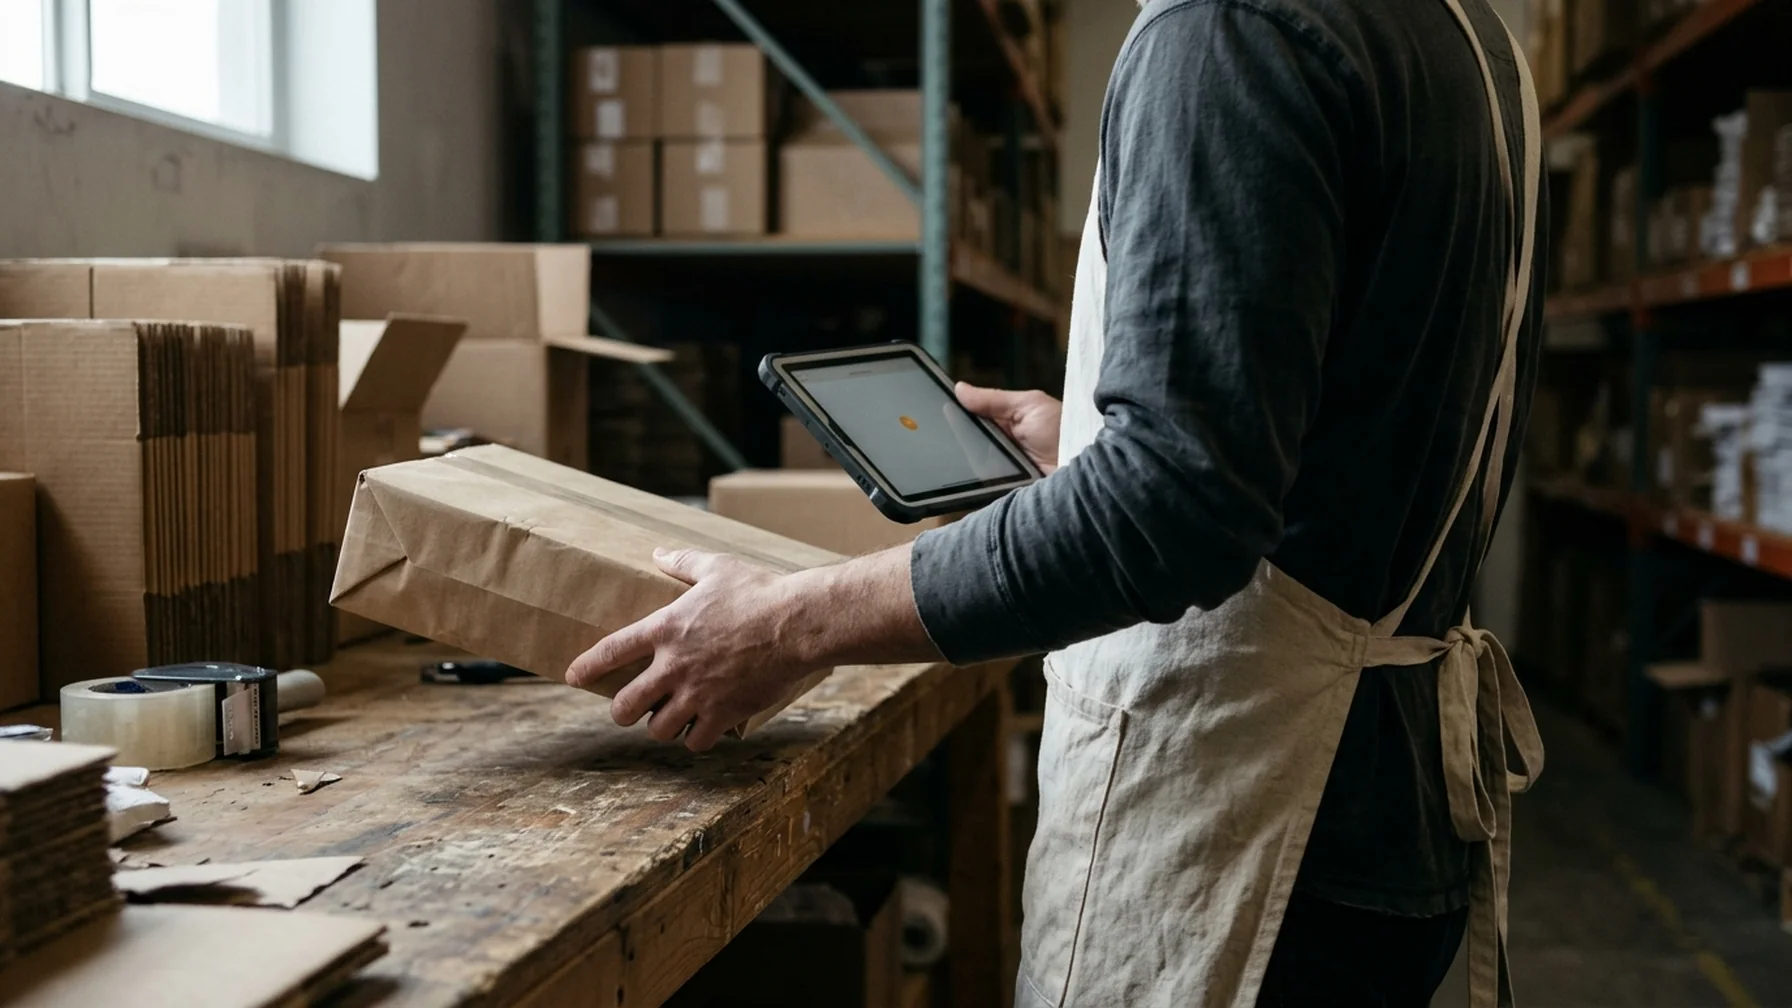
A fulfillment worker holding a parcel at a packing bench while checking an alert on a tablet

Alerts that arrive while you can still act

A dispute filed 40 days after delivery is harder to answer than a fraud alert at checkout. Route high-value orders, mismatched billing addresses and repeat refund requests to a person who can call the customer or hold the shipment. Track how many alerts turn out to be real fraud so the queue stays worth the staff time.

Route fraud alerts to a reviewer

Chargeback prevention

Fewer disputes start with clearer billing

Most chargebacks begin as unrecognized charges, so the descriptor on a customer's statement and the receipt you send do more to prevent disputes than any recovery tool.

Read chargeback prevention articles

Email updates

Get new fraud and chargeback write-ups by email

One email when we publish a new guide on chargeback prevention, fraud scoring, or risk operations. No newsletter schedule, no promotions.

We use your address only to send these updates. Unsubscribe from any email; we delete the address when you do. We do not sell or share it.